ResearchMonthly Index
The Sassaman Index
Fundraising conditions for emerging private fund managers
August 2026Published Next reading
This is the August 2026 edition, preserved as published. View the current reading
- Frozen0–20
- Tight20–40
- Balanced40–60
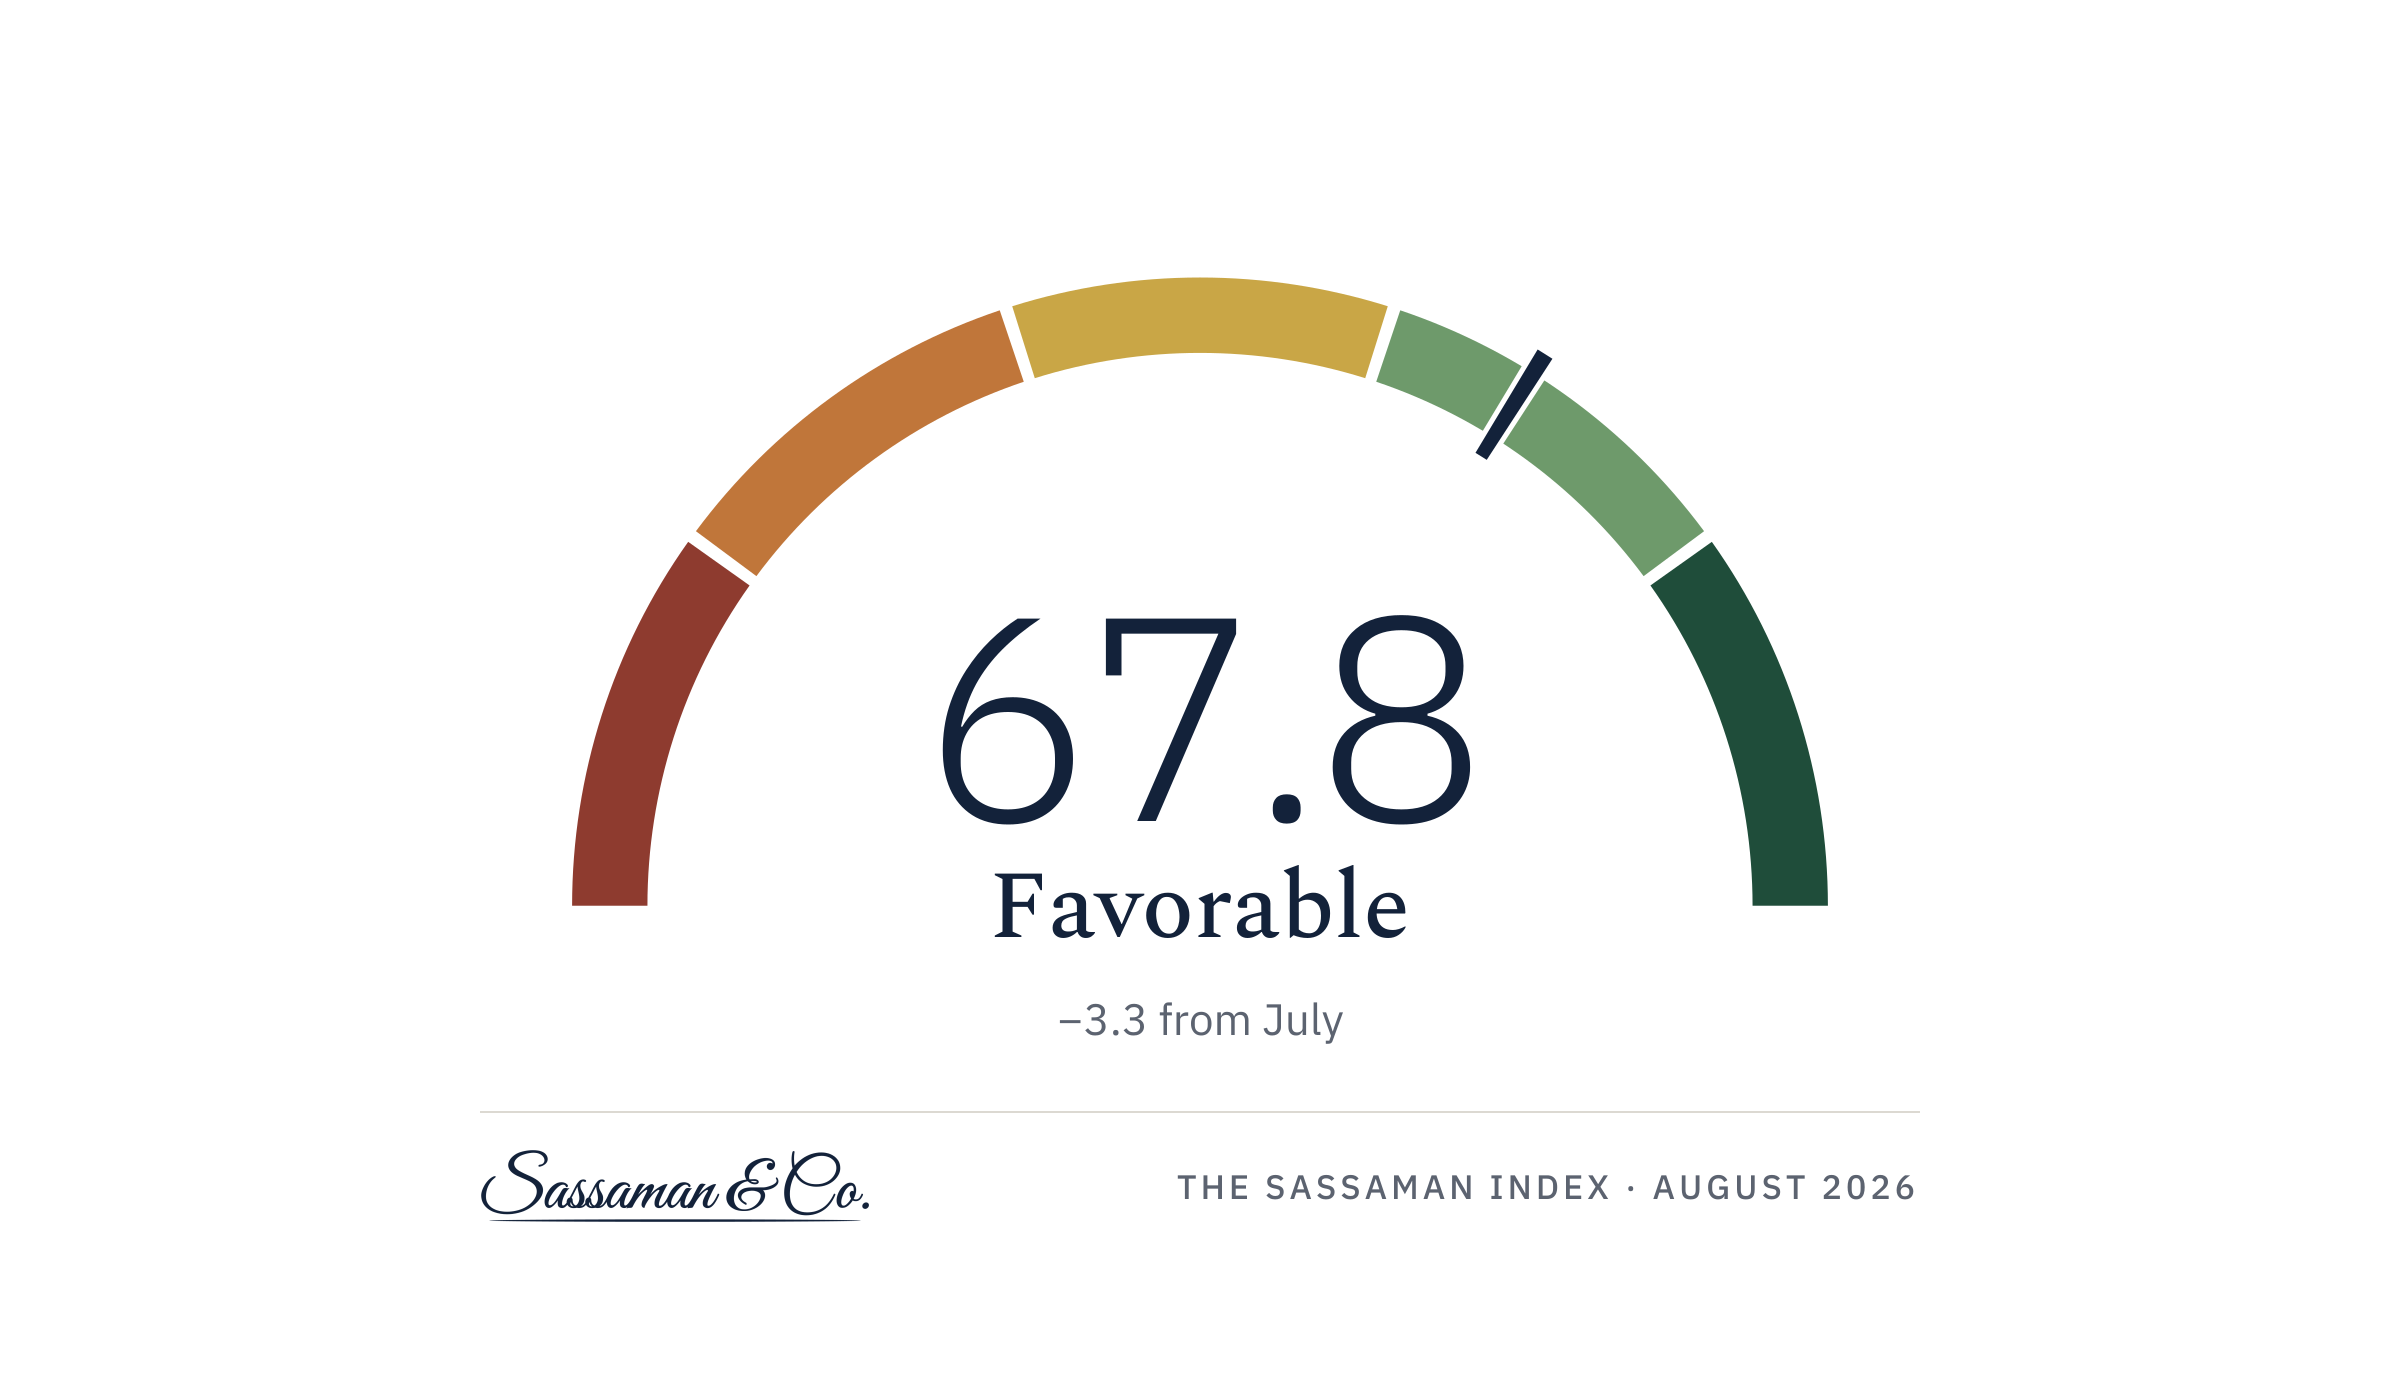
- Favorable60–80 (current)
- Hot80–100
- Index reading
- 67.8
- Condition
- Favorable
- Change from July
- −3.3
- Change over twelve months
- +18.8
- Methodology
- Version 1.0.0
Commentary
Index history
+18.8 since Aug 2025 (one year)
Dashed line: readings before August 2026 are backfilled using the current methodology and were not published in real time.
View data table
| Month | Reading | Note |
|---|---|---|
| August 2026 | 67.8 | |
| July 2026 | 71.1 | Backfilled |
| June 2026 | 73.0 | Backfilled |
| May 2026 | 68.8 | Backfilled |
| April 2026 | 63.9 | Backfilled |
| March 2026 | 55.2 | Backfilled |
| February 2026 | 62.6 | Backfilled |
| January 2026 | 61.5 | Backfilled |
| December 2025 | 54.0 | Backfilled |
| November 2025 | 57.7 | Backfilled |
| October 2025 | 54.5 | Backfilled |
| September 2025 | 53.3 | Backfilled |
| August 2025 | 49.0 | Backfilled |
The Sassaman Index is published monthly. Receive each edition by email, or read our research on Substack.
What moved
The Index eased to 67.8 in August from 71.1 in July, its fifth consecutive month in the Favorable band. The decline came mainly from credit conditions: the Moody's Baa corporate spread averaged 1.63 percentage points, up from 1.59 in July, lowering that component to 73 from 82. Fund launch activity was little changed.
Where it stands
First-time fund activity remains strong. In the six months through August, 488 first funds came to market, up 25% from 391 a year earlier, and 499 second and third funds launched, up 23%. Established managers grew faster still, with total new fund launches up 35%, so emerging managers' share of new funds slipped to about 35%. That share was the weakest component this month. Only 17% of months since 2014 have read higher than August.
What to watch
Short-term rates are the main headwind. The 2-year Treasury yield averaged 4.22% in August, about half a point above a year earlier, and has averaged 4.60% so far in September. Credit spreads have narrowed again in September. The September reading, due October 6, will show whether higher short-term rates begin to weigh on new fund launches.